Does Insurance Cover Water Damage
Does Insurance Cover Water Damage?
Does insurance cover water damage? It depends on the cause of the damage and the terms of your policy. Sudden and accidental damage, like a burst pipe, is often covered. Gradual damage, like a slow leak that went unrepaired for months, usually is not.
DALLAS WATER RESCUE
The Short Answer
Floodwater rising from outside almost always requires separate flood insurance.
We make no coverage promises here. Every policy differs. What this page does is explain the types insurers use, so you can read your policy and talk to your agent with a clear head.
DALLAS WATER RESCUE
Sudden Vs Gradual Damage
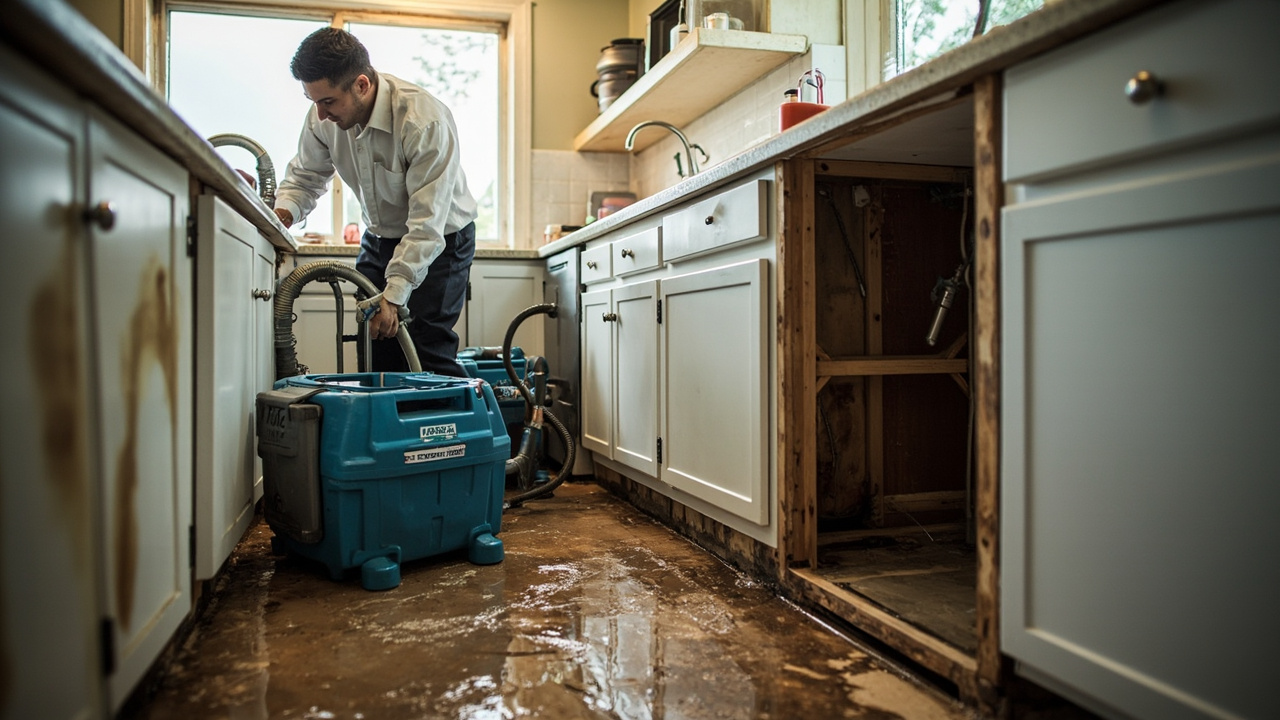
Sudden and accidental damage happens in a single, unexpected event. Examples Dallas homeowners know well:
- A pipe bursts during a winter freeze, the same way pipes burst across DFW in the February 2021 freeze.
- A washing machine supply hose fails and floods the laundry room in minutes.
- A water heater ruptures and floods the garage.
This type of damage is often covered under standard homeowners policies.
Gradual damage develops over time and could have been prevented with maintenance:
- A slow drip under a kitchen sink, ignored for months, rots the cabinet base and subfloor.
- A shower grout line that failed years ago, soaking the wall behind it.
Insurers commonly exclude gradual damage on the grounds that the homeowner had time to act. This is why fast mitigation matters even before the claim question is settled: stopping the damage now keeps a small covered event from turning into a large uncovered one.
INSURANCE GUIDE
Flood Insurance Vs Homeowners Insurance
Rising water from outside is treated as flood, not water damage, and standard homeowners policies often exclude it. Dallas gets sudden severe thunderstorms and flash flooding, and homes near the Trinity River floodplain face real rising-water risk. If outside water entered your home during a storm, a standard homeowners policy likely will not respond.
Separate flood insurance exists for exactly this. Check whether you carry it before you assume anything. After a flood event, call your flood insurer first and a restoration company immediately: contaminated floodwater is sewage or floodwater and should not wait.
DALLAS WATER RESCUE
Common Exclusions Vary By Policy
Exclusions commonly found in homeowners policies include:
- Floodwater from outside the home.
- Gradual leaks and long-term seepage.
- Damage from neglect or failed maintenance.
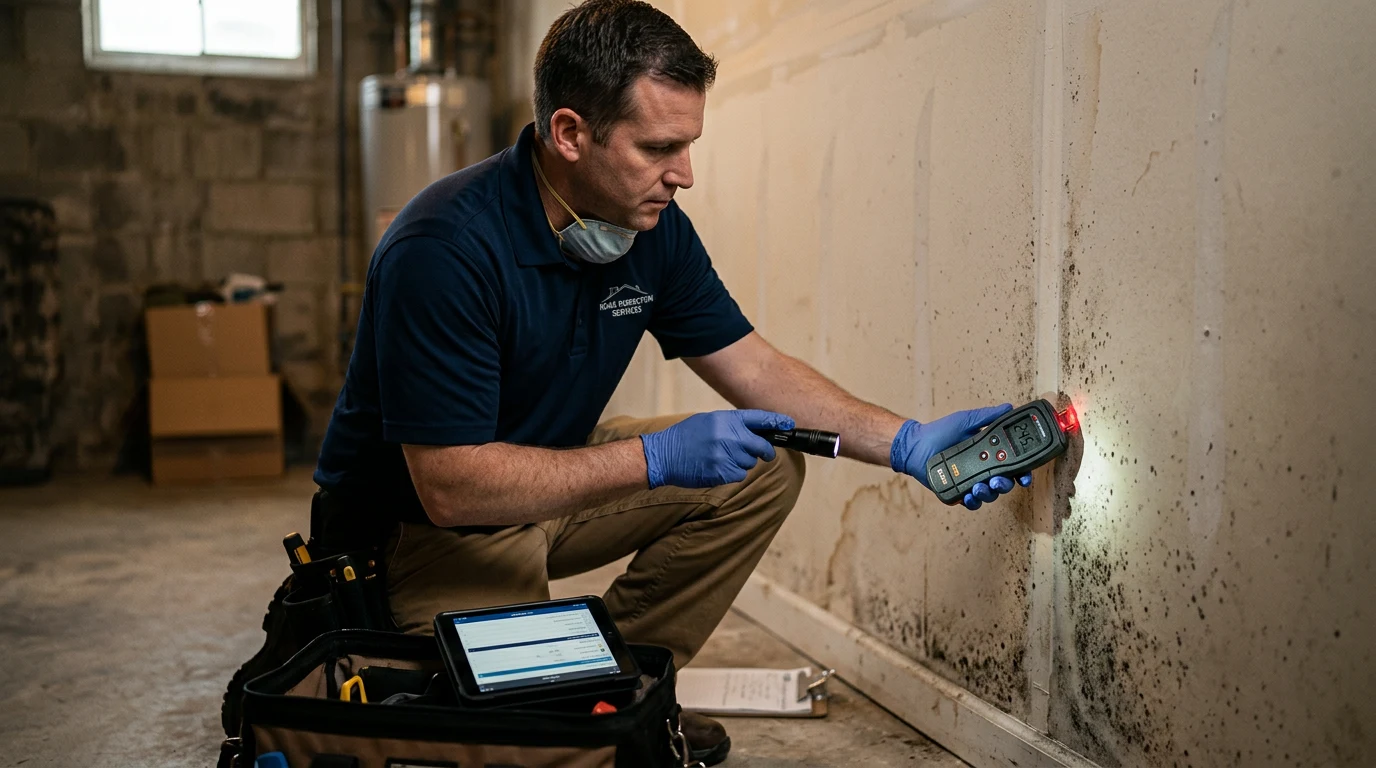
- Mold damage tied to an uncovered cause or delayed mitigation.
Every policy differs, and endorsements change what is included. Read your policy or call your agent. We do not decide coverage and we do not promise it.
DOCUMENTATION
Documentation Checklist For Your Claim
Strong documentation is the difference between a smooth claim and a fight. Gather:
- [ ] Photos and video of the damage before any cleanup, taken from multiple angles.
- [ ] A written list of damaged items, room by room.
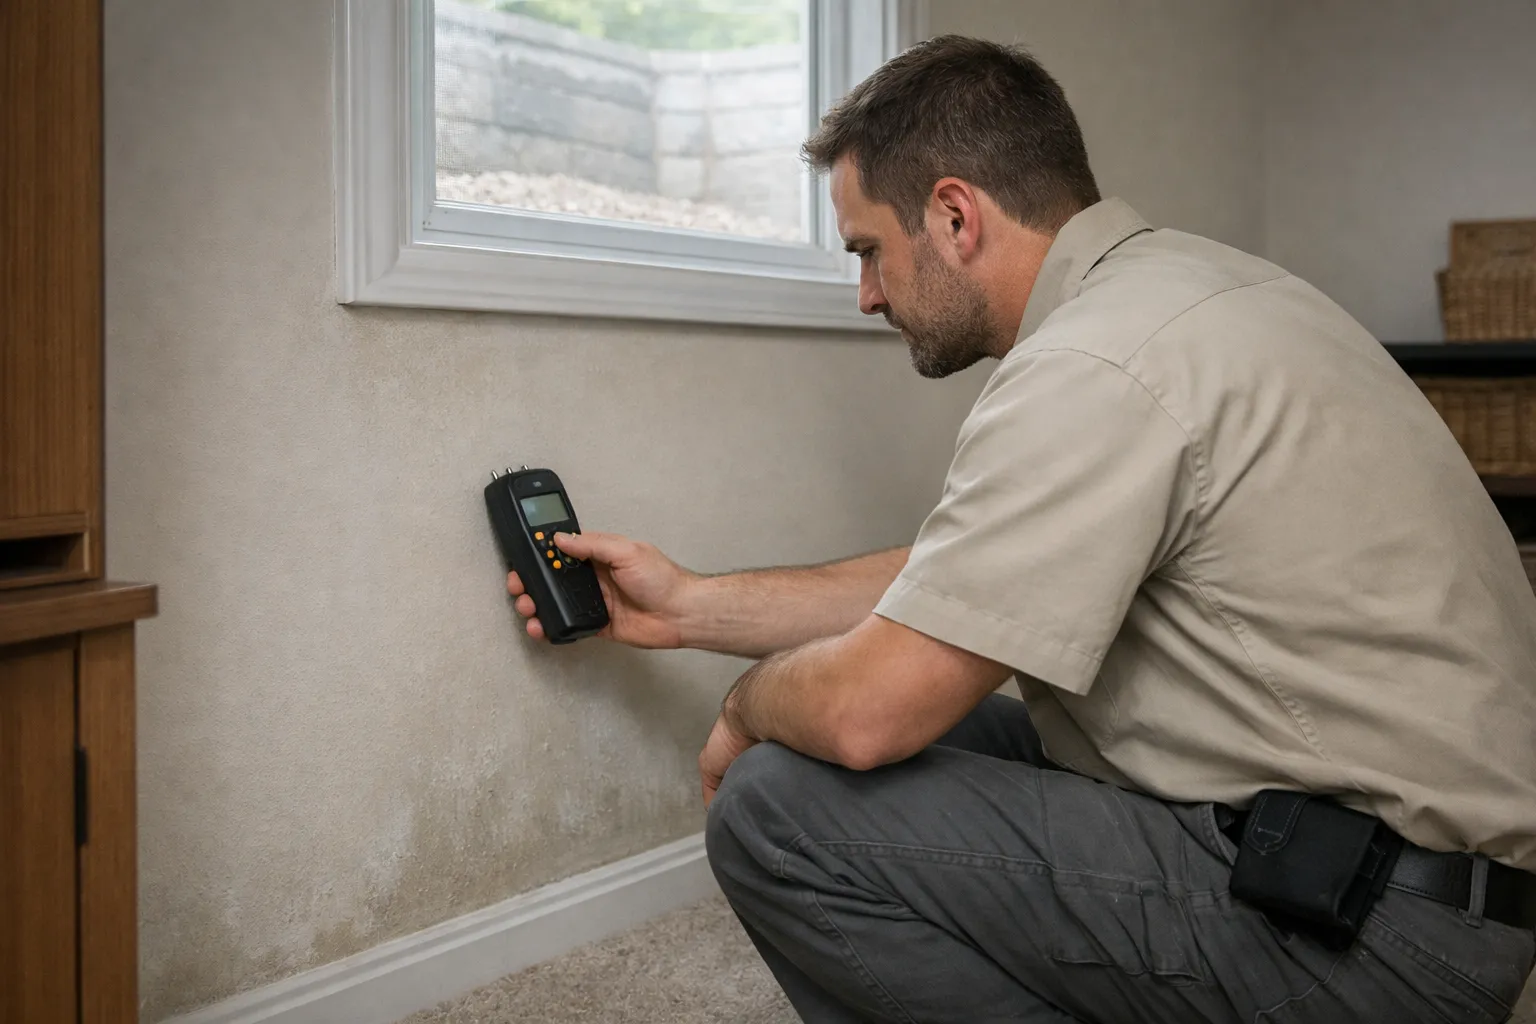
- [ ] Moisture readings and drying logs from the restoration company. We document readings at every monitoring visit, and these logs prove the work was necessary and complete.
- [ ] All receipts for emergency work, hotel stays, and supplies.
- [ ] A written log of every call with the insurer: date, name of the person you spoke with, claim number, and what was said.
Take photos first. Cleanup can wait a few minutes. Documentation cannot be recreated after the fact.
DALLAS WATER RESCUE
Adjuster Vs Contractor: Different Roles
The insurance adjuster works for the insurance company. Their job is to evaluate the claim under the policy terms.
The restoration contractor works for you, the property owner. Our job is to stop the damage, dry the structure to verified readings, and document everything so the claim file is complete.
Both need documentation. We provide it: photo documentation, moisture mapping, daily drying logs, and itemized estimates that separate mitigation from repair. Hand those to your adjuster and the conversation changes.
DALLAS WATER RESCUE
Can I Choose My Own Restoration Company In Texas?
Yes. Texas homeowners can choose their own restoration contractor. Your insurer may suggest preferred vendors, but the choice is yours. Choose the company that shows you an itemized scope, documents moisture readings, and communicates clearly, not just the one your insurer names first.
Frequently Asked Questions
Usually not if the leak is gradual. Insurers commonly exclude slow leaks that developed over time and could have been fixed with maintenance. Sudden failures, like a burst pipe, are often covered. Check your specific policy.
Usually not. Standard homeowners policies often exclude rising water from outside, including flash flooding from Dallas thunderstorms. That coverage requires separate flood insurance, so check whether you carry it.
No. Start emergency mitigation right away and document everything with photos and video first. Waiting lets water spread and gives insurers grounds to cite neglect or delayed response. Mitigation stops the loss; documentation protects the claim.
We cannot predict premium changes. Premiums are set by your insurer based on your policy and claims history. If you are unsure whether to file, call your agent and ask before opening a claim, and get any advice in writing.
Yes. In Texas you choose your own contractor. We provide the itemized estimates, moisture logs, and photo documentation your adjuster needs, regardless of who recommended us.
DALLAS WATER RESCUE
Claim-Denied Next Steps
If your claim is denied:
- Ask for the denial in writing, with the specific policy exclusion cited.
- Read the cited exclusion against your actual policy language.
- Consider a second opinion, either from your agent or an independent review of the denial.
A denial is a starting position, not always the final word. Whatever happens with the claim, the water still needs to come out.
Does Insurance Cover Water Damage
Call Now: (972) 430-9181. Itemized estimates and documented drying on every job.
Call Now: (972) 430-9181